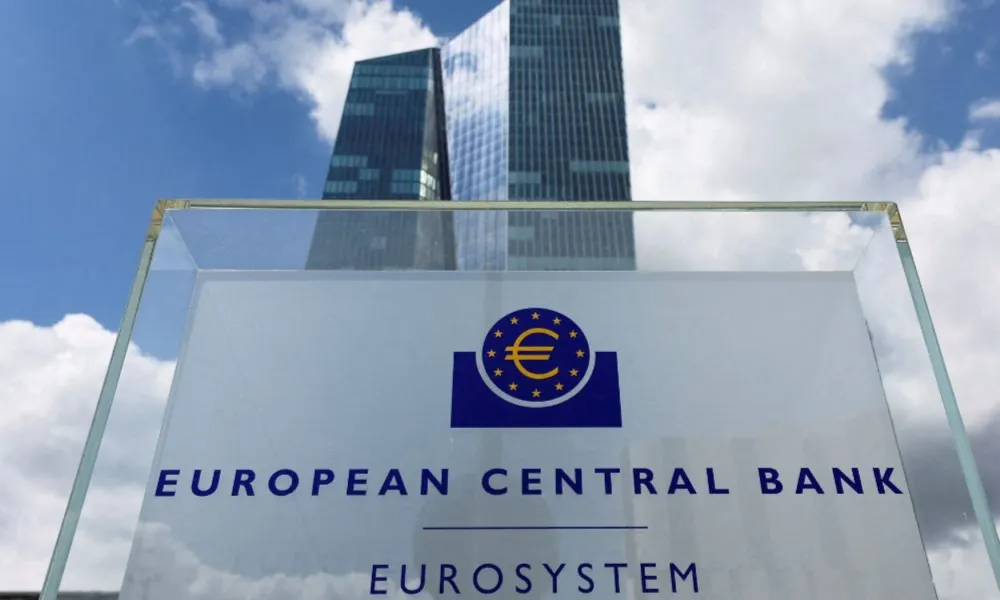
Households across the eurozone have accumulated substantial savings, but much of that money remains in low-return bank deposits rather than being channelled into investments, according to the European Central Bank (ECB).
An ECB blog says almost one-third of household financial wealth, equivalent to around €10 trillion, is held in cash and bank deposits, while 80% of eurozone households do not own shares or other financial products linked to capital markets.
The blog was authored by Andrei Dumitrescu, Zakaria Gati, Justus Meyer, Laura Parisi and Alessandro Spolaore.
Investment gap weighs on households and Europe
The ECB argues that limited participation in capital markets affects both individual households and the European economy.
For savers, greater access to investments could offer the possibility of higher long-term returns and greater diversification, potentially helping households accumulate more wealth over time.
At the broader economic level, keeping such large amounts in deposits limits the pool of capital available to finance innovation, productivity and long-term economic growth in Europe.
The ECB said better access to capital markets could help households achieve higher returns and diversify their investments, but stressed that different groups face different obstacles and will require a combination of policy measures.
Successful initiatives already introduced in several eurozone countries could provide examples for future action.
Europeans favour deposits and property
According to the authors, European households traditionally favour bank deposits and real estate, contrasting sharply with US households, which participate much more extensively in capital markets.
The difference persists even among Europeans in higher income and wealth brackets, whose participation in investment products remains notably lower than among comparable US households.
The ECB identifies several reasons for this reluctance beyond households' purely financial constraints.
These include limited financial literacy, low levels of trust in financial markets and perceptions that investing carries excessive risk.
ECB proposes financial education
Among its recommendations, the ECB calls for stronger financial education to help consumers understand the opportunities and risks associated with different financial products.
Slovenia is highlighted as an example of what can be achieved through a systematic approach.
Its National Financial Education Programme, introduced in 2010, has helped the country reach one of the highest levels of financial literacy in the European Union.
The ECB argues that increased understanding of personal finance could give more households the confidence and knowledge required to consider alternatives to conventional deposits.
Simpler investment products
The ECB also stresses the importance of providing investment products that are simple, transparent and easily accessible.
Finland is cited as an example, where equity savings accounts have helped encourage greater participation in capital markets.
By the end of 2024, 37% of Finnish households held investment funds, listed shares or both.
Such schemes, the ECB suggests, could help lower some of the practical barriers preventing ordinary savers from investing.
Pension reforms could widen participation
Pension systems represent another potential route for directing savings towards capital markets without requiring households to make complex investment decisions themselves.
The ECB points to the Netherlands, where households benefit from capital-market returns through compulsory occupational pension schemes.
The model allows individuals to build long-term wealth through market investments without having to actively select and manage those investments themselves.
According to the ECB, this can be particularly valuable for households with limited time, financial resources or investment expertise.
Capital markets and European competitiveness
The ECB's recommendations include greater financial education, simpler and more transparent investment products and pension reforms capable of directing a larger share of European savings into capital markets.
The underlying objective is not only to improve households' opportunities to accumulate wealth, but also to mobilise Europe's substantial pool of private savings towards productive investment.
With around €10 trillion currently held in cash and deposits, even a partial shift towards investment could provide additional financing for businesses, innovation and productivity, contributing to Europe's competitiveness and long-term economic growth.